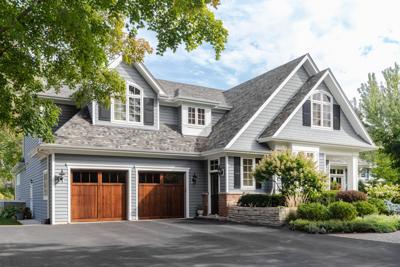

Naperville, IL, USA - A large grey and white modern farmhouse with two wooden garage doors, and beautiful landscaping.
For some first-time buyers, the down payment is the biggest obstacle between where they are and a set of house keys. It requires months or years of deliberate saving, and the goalpost can feel like it keeps moving as home prices shift. But the buyers who get there fastest usually follow a repeatable system rather than trying harder at random. This guide breaks down effective strategies, from building the right savings structure to finding money you might be leaving on the table.
Start With a Concrete Target Number
Vague goals don't produce savings. Before you open a dedicated account, calculate what you actually need. A 20% down payment is the traditional benchmark, but many loan programs accept significantly less. FHA loans allow as little as 3.5% down, and conventional options are available at 3% for qualified buyers. Factor in closing costs, which typically run 2% to 5% of the purchase price, and set aside a modest reserve for immediate repairs and moving expenses. Running these numbers against realistic home prices in your target area gives you a specific dollar amount to work toward rather than an abstract aspiration.
People are also reading…
You Could Open a Dedicated High-Yield Savings Account
One of the simplest changes with real impact: you can potentially separate your down payment money from the account you use daily. When savings live alongside your grocery budget, they tend to get raided. A high-yield savings account at an online bank keeps the funds accessible but out of sight, and the interest rate — often four to five times higher than a traditional savings account — adds meaningful growth over an 18-to-36-month saving horizon. You could name the account something concrete, like "House Fund," to reinforce the purpose every time you log in.
Automate Before You Can Spend It
Manual transfers require discipline every single time. Automation requires it only once. Set up a recurring transfer from your checking account to your house fund on the same day your paycheck arrives. Even a modest fixed amount builds faster than sporadic larger contributions, because consistency compounds and removes the willpower equation entirely. If you get a raise, automatically increase the transfer amount. Treat the house fund the same way you'd treat a non-optional bill.
Audit Your Spending for Hidden Savings Room
Most people underestimate where their money actually goes. Pull three months of bank and credit card statements and categorize every transaction. Subscriptions that went unnoticed, dining habits that crept up, or recurring services you no longer use often reveal $100 to $300 a month in recoverable savings without meaningful lifestyle changes. Redirect that amount to your house fund immediately. This exercise is worth doing once at the start of your saving plan and again every six months as spending patterns shift.
Accelerate With Windfalls and Side Income
Tax refunds, work bonuses, gifts, and freelance income are natural accelerators. Commit to directing a fixed percentage — 50% or more — of any windfall directly to your down payment fund before it blends into your regular spending. If you have marketable skills, a focused side project during your saving period can move your timeline forward by months. The key is treating windfall income as an exception to your normal spending rules rather than an invitation to splurge.
Know How Market Conditions Affect Your Timeline
The housing market doesn't sit still while you save, and understanding current buyer behavior can inform how you plan. Some 58% of first-time buyers who shifted their original nonnegotiables did so because of affordability pressures, according to Rocket Mortgage's data on shifting buyer priorities. That's a signal worth noting: buyers who remain flexible about what they require on day one tend to reach ownership sooner. A slightly smaller home in a nearby zip code might mean six fewer months of saving, which translates directly to months of building equity instead.
Research Down Payment Assistance Programs
Many first-time buyers don't realize how many assistance programs exist at the state, county, and city level. These include grants that don't need to be repaid, forgivable loans, and matching programs tied to income thresholds. The U.S. Department of Housing and Urban Development (HUD) maintains a database of programs by state, and many lenders can walk you through options available in your specific market. These programs can add thousands of dollars to your effective down payment without requiring additional saving on your end.
Track Progress and Adjust the Plan
A savings plan that made sense at the start may need adjusting as circumstances change. Review your down payment progress monthly, compare it against your target, and recalculate your timeline. If you've had a good income month, increase the next month's transfer. If an unexpected expense hit, decide in advance how you'll make it up rather than treating the setback as an excuse to pause. Buying your first home is a long project, and the buyers who get there are often the ones who stay consistent even when the timeline stretches.